
Seven Bank Group Integrated Report 2026 Message from the Officer in charge of Financial Strategy
Driving Top-Line Growth and Margin Improvement to Enhance Corporate Value
FY2026: A Fresh Start in Restoring Profitability and Capital Efficiency
Managing Executive Officer
In charge of Planning Division and General Manager, Planning Division
Ken Shimizu
Review of FY2021-2025 Medium-Term Management Plan
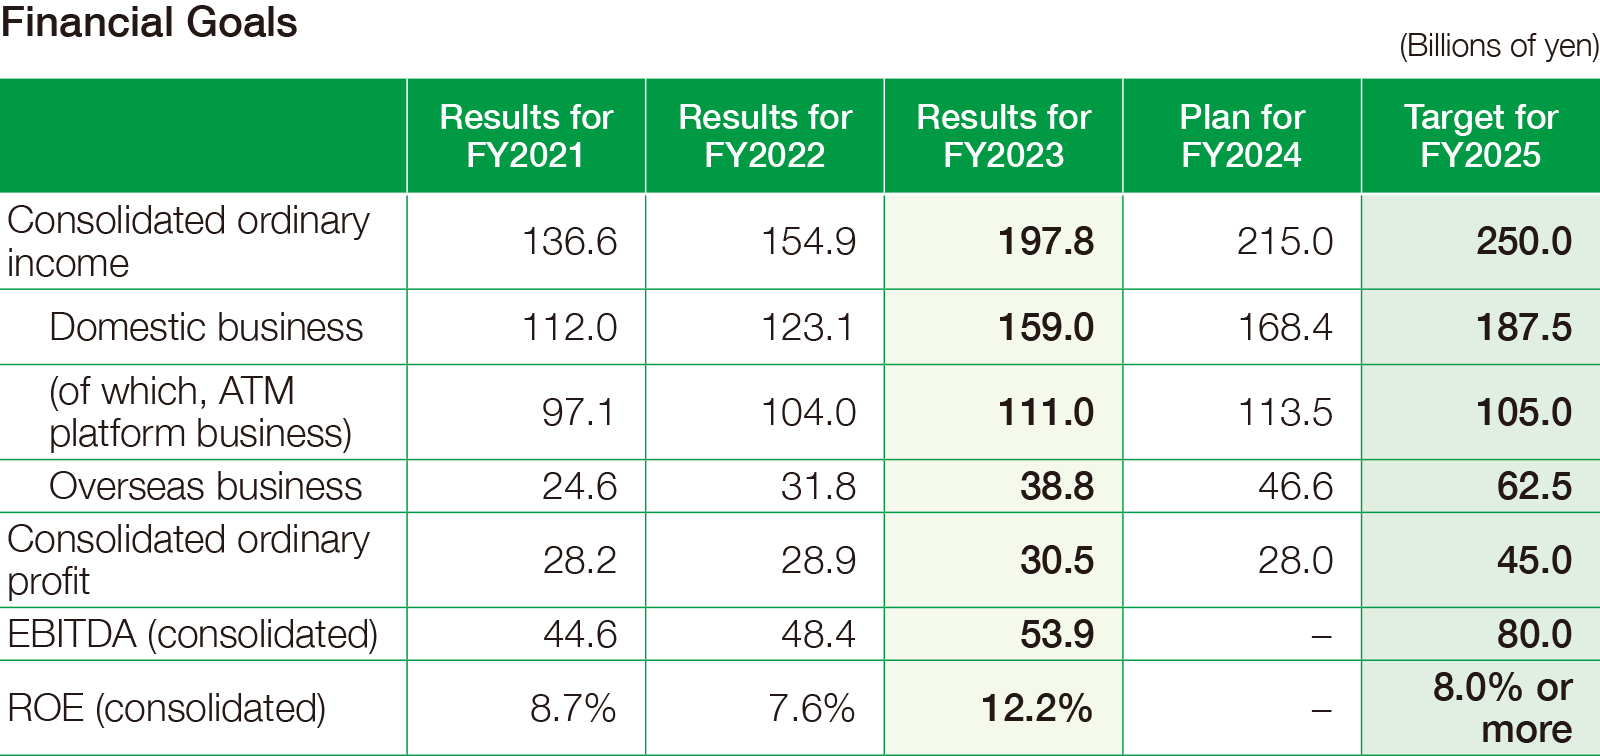
In FY2025, consolidated ordinary income reached a record high of 220.0 billion yen. However, consolidated ordinary profit declined to 30.1 billion yen, while net income fell sharply to 13.4 billion yen primarily due to factors such as the recording of impairment losses of 8.4 billion yen related to the credit card business. As a result, ROE (return on equity) fell to 4.8%, and all of the financial goals set in the previous Medium-Term Management Plan—consolidated ordinary income of 250.0 billion yen, consolidated ordinary profit of 45.0 billion yen, and ROE of 8% or more—were not met.
We have identified three principal factors behind the shortfall. The first is the credit card business. When we made Seven Card Service a consolidated subsidiary in 2023, we planned to expand the membership base, primarily centered on Seven-Eleven customers, but we were unable to achieve the expansion we had anticipated. The second reason is the overseas business. In the United States, plans to diversify services in areas such as the loan business did not progress as expected. In Indonesia and the Philippines, performance was constrained by material changes in market conditions, including intensified competition. The third factor was our insufficient allowance for changes in key macroeconomic assumptions. The plan was developed on the premise of a deflationary environment and did not adequately factor in higher funding costs resulting from rising interest rates or increases in operating expenses caused by inflation. We recognize the seriousness of having fallen short of our medium-term targets. Based on this analysis, we will address the underlying structural issues and restore a sustainable earnings growth trajectory.
At the same time, over the past five years, we have built a solid foundation for future growth through a number of tangible achievements. Our core domestic ATM business reached a record high of 28,536 installed ATMs and 1.12 billion total transactions as of the end of FY2025. Furthermore, the “+Connect” service, which launched in 2023, has been adopted by over 50 companies, with particularly strong adoption by regional banks. Recently, our service that allows people to receive local government benefits at ATMs has been performing well, and the number of local governments introducing the service has expanded rapidly over the past year. Furthermore, steady progress was made in diversifying the business portfolio. Retail deposits reached ¥652.4 billion, with 3.50 million accounts and a personal loan balance of ¥79.2 billion. Although we did not meet our goals in the overseas business, consolidated ordinary income achieved a five-year compound annual growth rate (CAGR) of 9.9%, and in FY2025, we achieved profitability in all four countries: the United States, Indonesia, the Philippines, and Malaysia.
New three-year outlook (FY2026-FY2028)
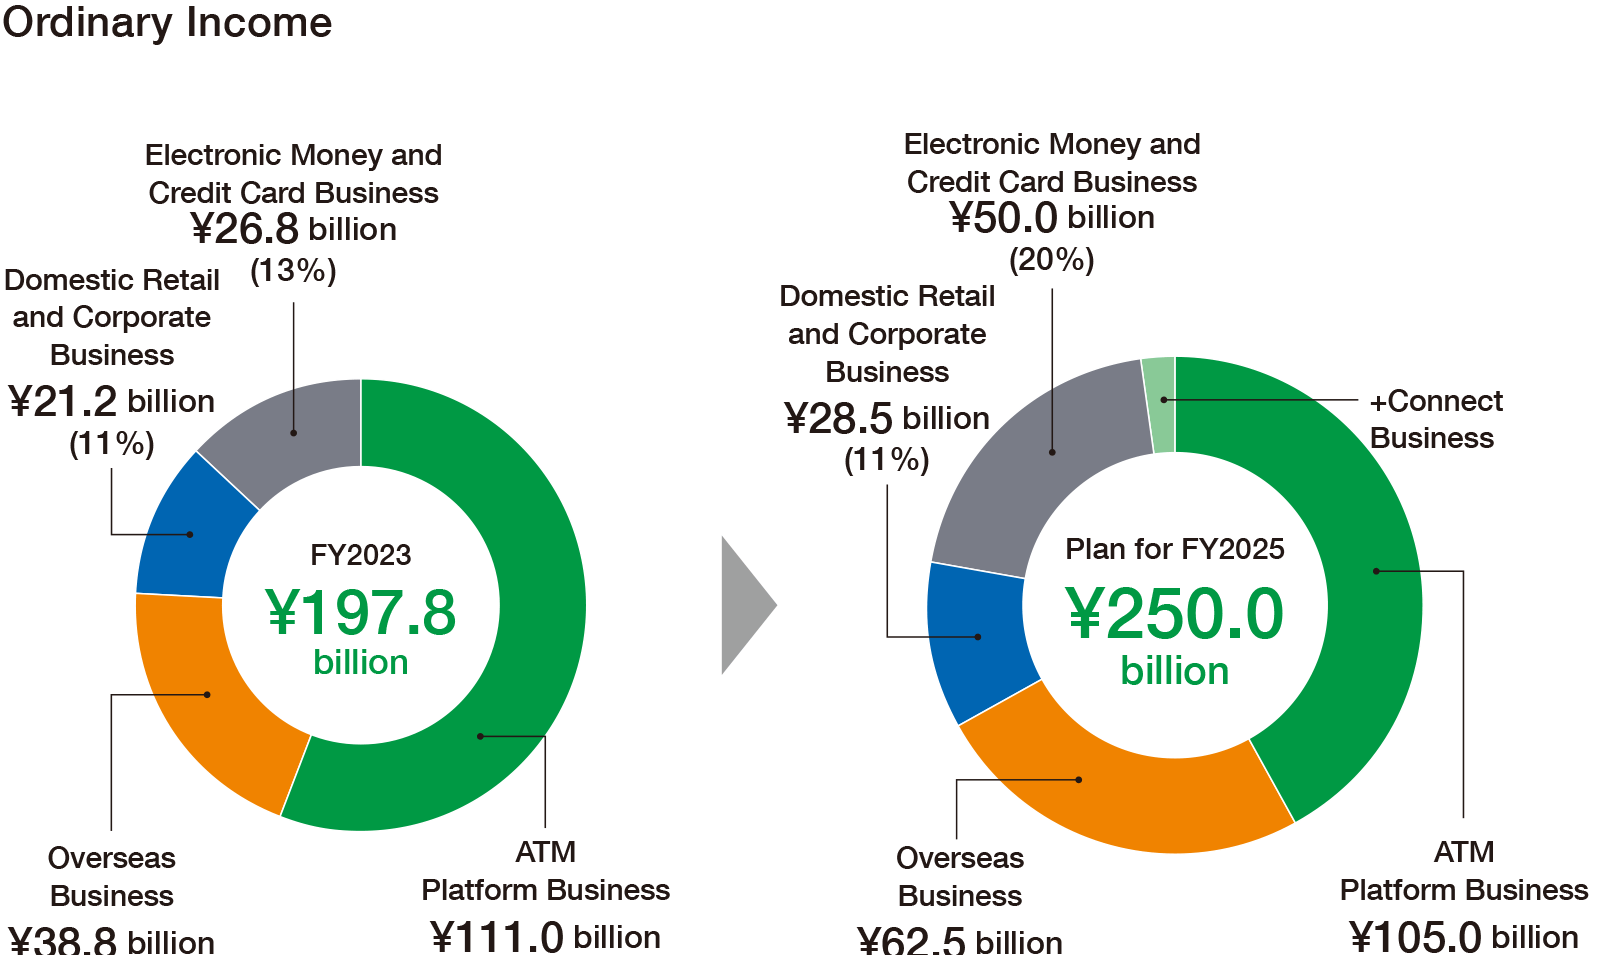
When we announced our results for the fiscal year ended March 31, 2026, we also presented a three-year outlook through FY2028. It sets targets of ¥280.0 billion in consolidated ordinary income, ¥40.0 billion in consolidated ordinary profit, and ROE of at least 8%. We deliberately chose a three-year outlook rather than a conventional Medium-Term Management Plan. Macroeconomic conditions and technology are changing so rapidly that the assumptions underlying a detailed business plan may quickly become outdated. We therefore intend to retain the flexibility to adapt our actions swiftly as conditions evolve, while making a firm commitment to the quantitative targets that must be achieved to enhance corporate value. We believe that delivering on these commitments is essential to restoring investor confidence. These targets are not based on optimistic assumptions. They start from a strengthened balance sheet following the recognition of impairment losses on underperforming businesses and incorporate clearly identifiable drivers of growth. In the first year, FY2026, we are still in the midst of structural reforms, and have projected increased income but decreased profits, with ordinary income of 235.5 billion yen and ordinary profit 29.5 billion yen. However, from FY2027 onward, we intend to return to a robust growth trajectory, delivering sustained growth in both revenue and earnings.
Market valuation tends to be closely linked to the equity spread, defined as the difference between ROE and the cost of equity. Expanding this positive spread is therefore critical to enhancing corporate value. Our cost of equity, estimated using the capital asset pricing model, has risen to the mid-6% range as interest rates have increased and could rise further depending on future rate movements. By contrast, ROE declined to 4.8% in FY2025, resulting in a negative equity spread. On the other hand, ROE in FY2025 was only 4.8%, and the equity spread fell into negative territory, leading to disappointing results. The Company’s goal to achieve ROE of 8.0% or more by FY2028 has been set to sustainably widen the positive equity spread that consistently exceeds cost of equity, and thereby enhance our valuation in the capital markets. To this end, a fundamental improvement in ROE, which is the source of increased corporate value over the medium to long term, is necessary.
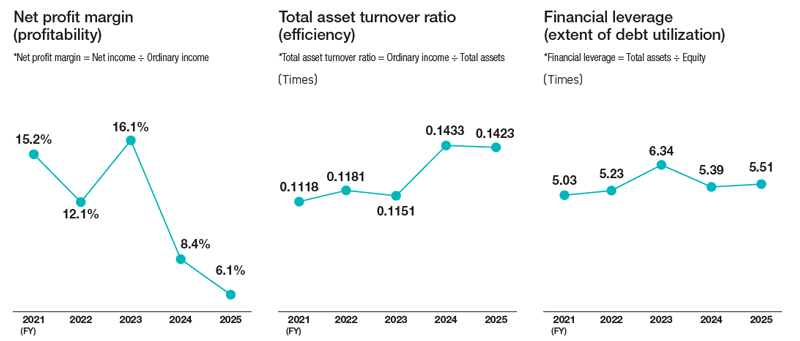
To identify the actions required to improve ROE, we have analyzed its three components: net profit margin, total asset turnover, and financial leverage. Asset efficiency and our financial structure have remained broadly stable in recent years. By contrast, net profit margin declined sharply from 8.4% in FY2024 to 6.1% in FY2025. This analysis makes clear that improving margins across each business is the principal lever for raising ROE to at least 8%. Therefore, in order to fundamentally improve our profit margins, we will be implementing the following initiatives over the next three years.
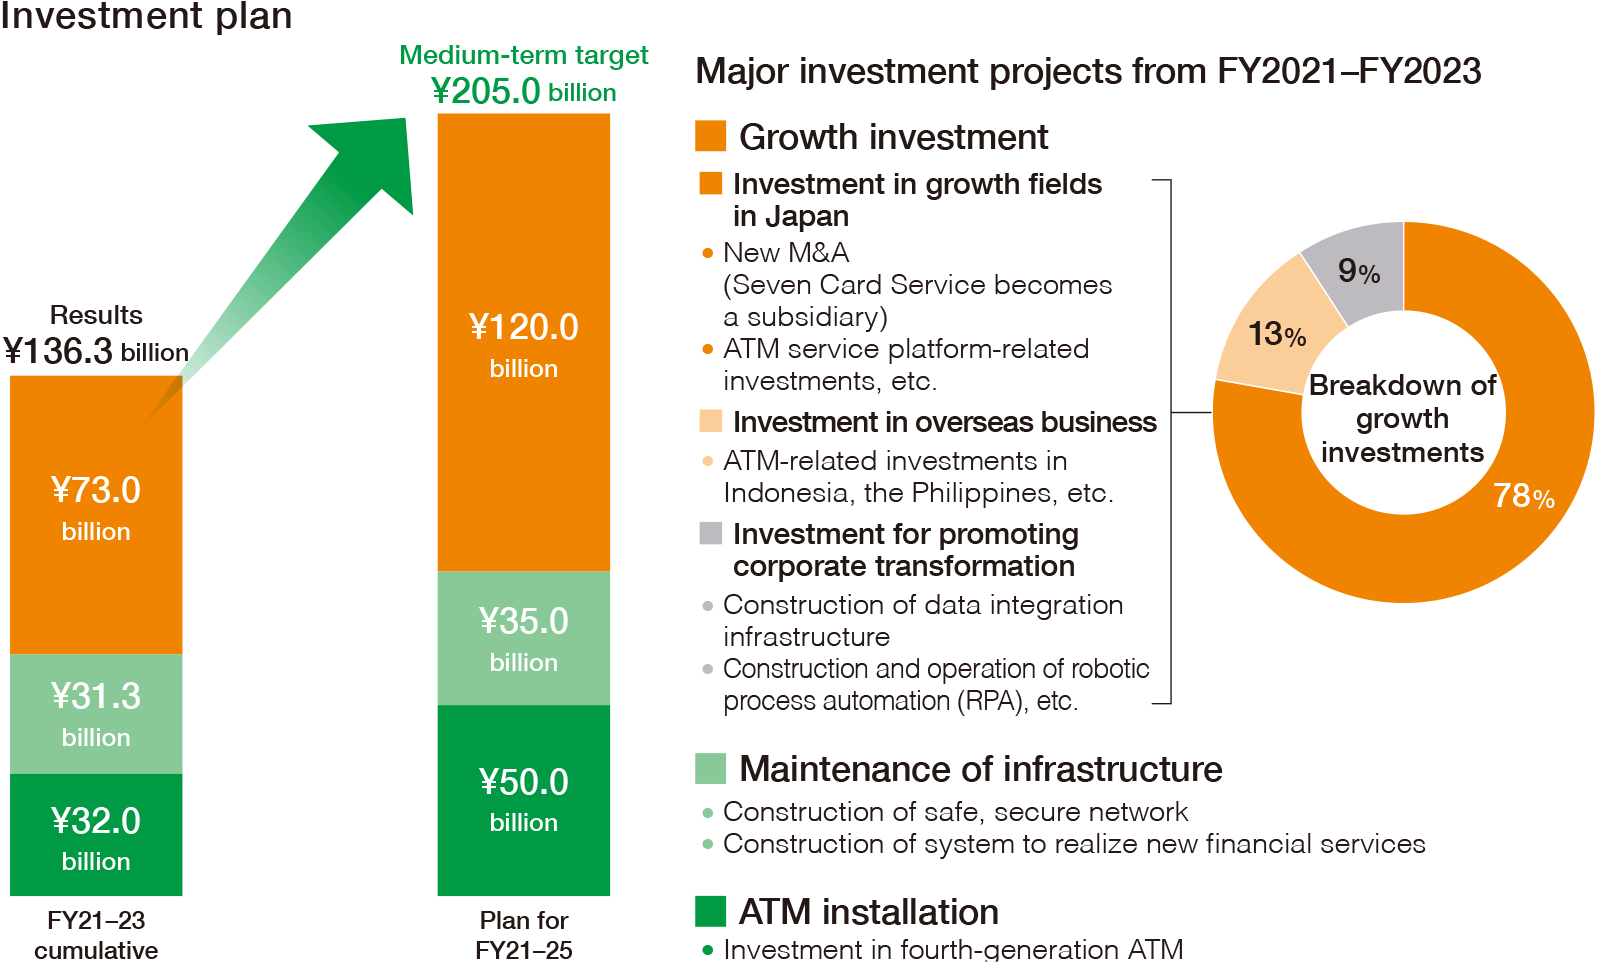
In the core ATM platform business, we will restore per-ATM profitability to an appropriate level. We are negotiating fee revisions with partner financial institutions to halt the decline in transaction fee rates. At the same time, we will increase both adoption and usage of +Connect to raise marginal profit per ATM. In addition, we will promote low-cost core deposit funding through the use of AI to reduce cash in ATMs and the acquisition of retail accounts, while appropriately controlling the risk of rising interest rates by issuing bonds at long-term fixed interest rates and acquiring time deposits, thereby ensuring appropriate profits even as funding costs and prices rise. Moreover, we began installing ATMs in FamilyMart stores as of June this year. This large-scale investment, involving the installation of approximately 16,000 units over approximately four years, should be a powerful driving force in boosting the Company’s top line and leading to solid profit growth.
The credit card business recorded approximately ¥8.0 billion in impairment losses in FY2025, and returning the business to profitability within the three-year period is an imperative. The launch of the new nanaco credit card in August will be a key catalyst for restoring net membership growth. We will also address the business’s high cost base by optimizing advertising expenditure and improve profitability while maintaining sound asset quality through disciplined growth in financial receivables.
In the overseas business, our U.S. subsidiary exceeded its targets in FY2025, entering a phase of strong profit contribution. On the other hand, performance in Indonesia and the Philippines has been sluggish due to factors such as increased competition. Going forward, We will rigorously assess investment returns in each market and manage the business with a stronger focus on capital efficiency, including the timely removal or relocation of underperforming ATMs. In parallel, we will work more closely with local partners to develop services tailored to each market and explore Beyond ATM business models, thereby improving the segment’s overall profitability.
Our domestic group companies will also contribute to consolidated profitability by expanding their fee-based businesses in response to growing demand from financial institutions. These include ACSiON, which provides fraud detection and anti-phishing solutions, and Bank Business Factory, which supports anti-money laundering operations and back-office processes.
New capital-raising options to support sustainable growth
Our deconsolidation from Seven & i Holdings, our capital and business alliance with ITOCHU Corporation, the impairment losses recorded in the credit card business, and the rollout of ATMs in FamilyMart stores beginning in June 2026 are all strategic foundations for the next phase of Seven Bank’s growth.
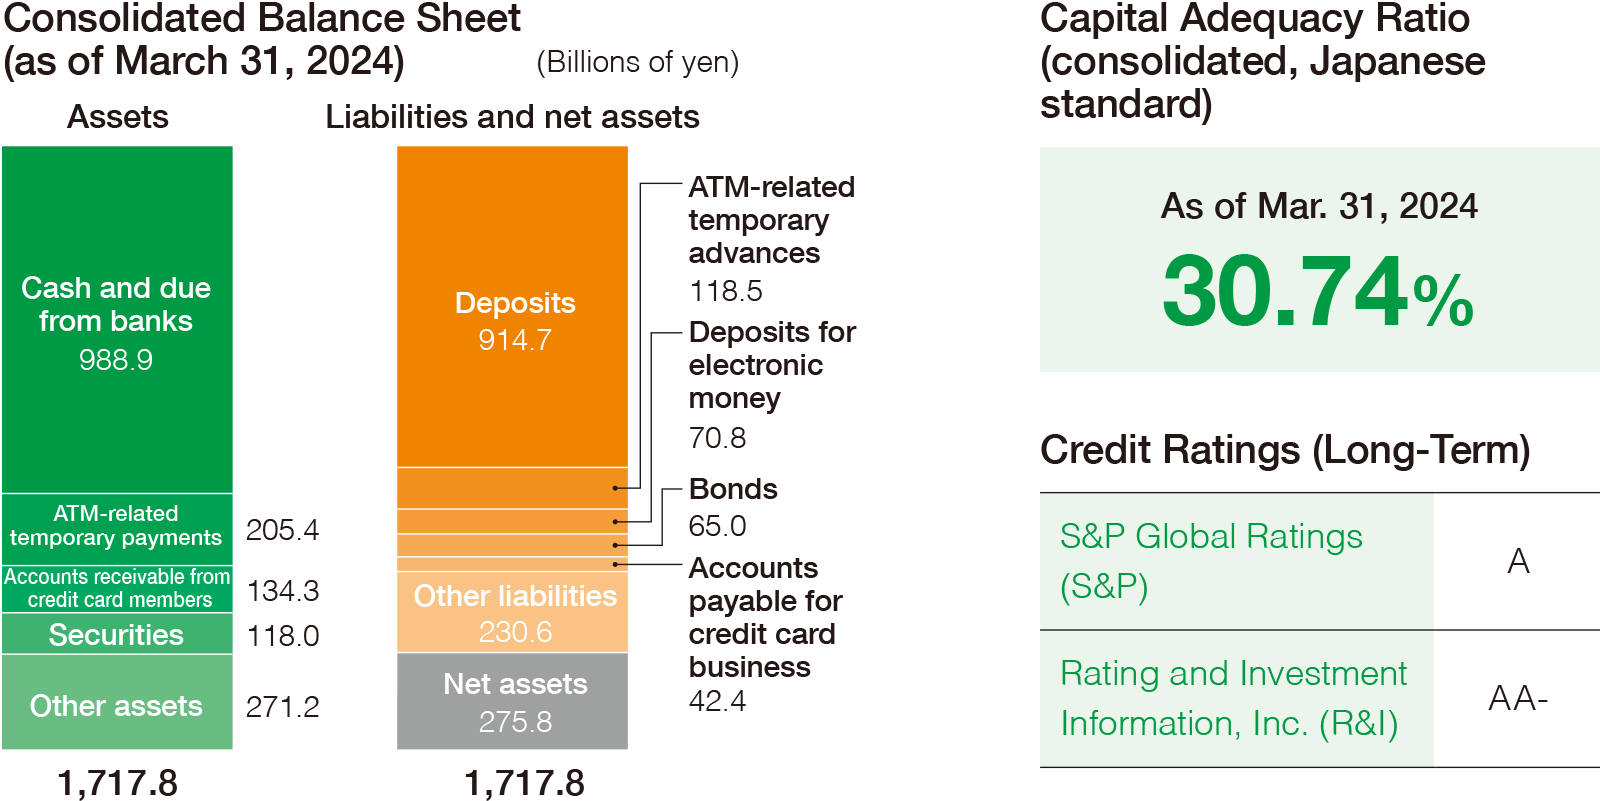
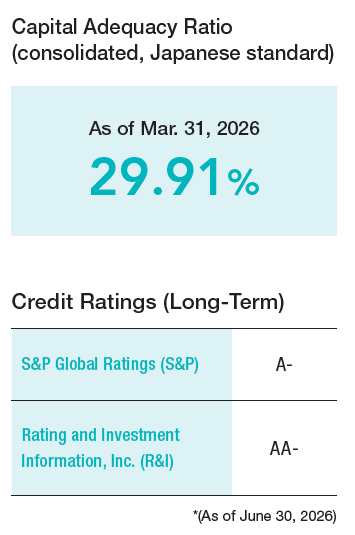
Our top priority at the moment is to improve the profitability of existing businesses, but if there are opportunities for significant growth that leverage the Company’s strengths going forward, we will pursue all possibilities. Our consolidated capital adequacy ratio is 29.91%, which is significantly higher than the Japanese standard. However, To preserve the flexibility to pursue growth opportunities, we must maintain a resilient financial foundation even amid rapid changes in the operating environment and retain the ability to raise growth capital when needed. Therefore, at the 2026 Annual General Meeting of Shareholders, we amended the Articles of Incorporation to authorize the issuance of preferred shares as an additional financing option. This framework gives us the flexibility to raise capital when required for major investments or in response to regulatory changes, while managing the risk of excessive dilution to existing shareholders and EPS that could result from issuing new common shares. It will support disciplined capital allocation by enabling us to pursue growth investment while protecting shareholder value.
A message for shareholders and investors
FY2026 is a “fresh start on our path back to a growth trajectory.” To enhance corporate value, it is important to generate returns that significantly exceed the cost of equity through thorough reforms of the revenue structure, and to sustainably widen the positive equity spread. To achieve this, it is essential to ensure an optimal balance between growth investments and shareholder returns.
Our top priority for growth investments is to invest in our domestic ATM platform business, which centers on the installation of approximately 16,000 ATMs in FamilyMart stores to discontinuously raise the top line. Furthermore, we will continue to invest in software, including the expansion of the “+Connect” platform, which is the source of our competitive advantage. These advance investments will ultimately lead to the creation of a strong income base for the future.
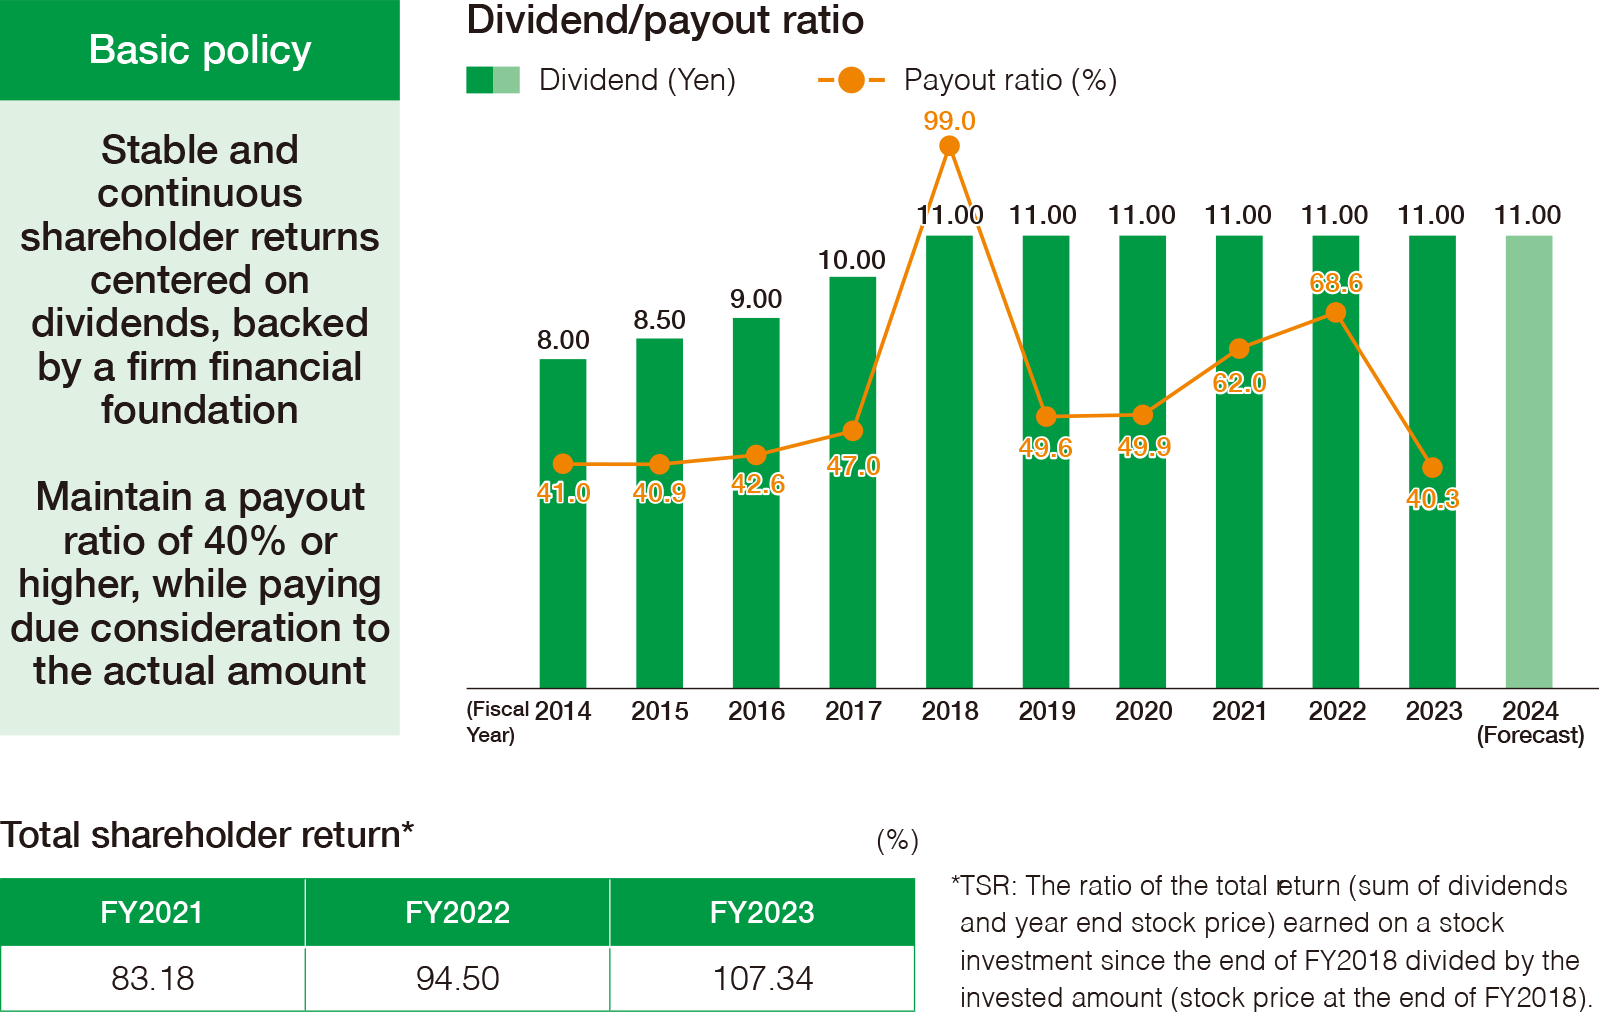
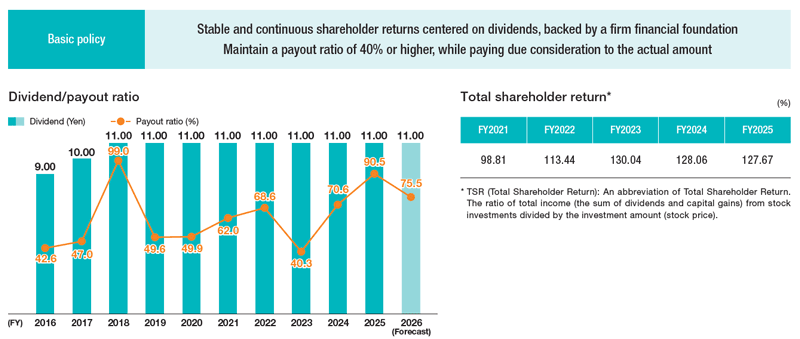
On the other hand, we will maintain our basic policy of a consolidated payout ratio of at least 40%, while also considering the absolute annual dividend and avoiding undue sensitivity to temporary fluctuations in earnings. Although impairment losses reduced EPS in FY2025, we maintained the annual dividend in absolute terms. For FY2026, we plan to maintain the dividend at ¥11.00 per share, representing a forecast payout ratio of 75.5%. Our strong operating cash flow and accumulated retained earnings provide a sound basis for maintaining shareholder returns.
We will continue to engage openly and transparently with our shareholders and investors. We sincerely appreciate your continued confidence and support as Seven Bank embarks on its next challenge: achieving a new leap in growth and corporate value.
- Management information
- Message from the President
- Management Policy, Management Environment, and Issues to be Addressed,etc.
- Risk Factors
- Risk Management Initiatives
- Compliance Initiatives
- Stock and bond information
- Stock Information
- Dividends and Shareholders Returns Policy
- Corporate Bond and Rating Information
- General Meeting of Shareholders
- IR Library
- IR News
- Financial Statements
- IR Presentations
- IR Calendar
- Annual report
- Seven Bank Disclosure Policy
- Other Corporate Information
- Company
- Sustainability